 Don’t just renew
Justworks health insurance: which of its two plan types you get, and how each one renews
Justworks is a PEO, a company that shares the employer role with you so it can run payroll, HR, and benefits. Its health insurance comes two ways: large group plans on policies Justworks holds for many companies at once, or small group plans bought in your company’s name. Which one you’re on decides how your price is set and when you renew.
The short version
- Medical, dental, and vision plans come with Justworks PEO Plus, listed at $124 a month per employee. PEO Basic, at $79, doesn’t include them.
- Justworks’ own “master policy” plans are large group plans, priced on your team’s makeup and past health insurance use.
- Its “open market” plans are small group plans in your company’s name, priced from the carrier’s rates for your area.
- Master policy plans renew on Justworks’ plan year, which now runs November 1 to October 31. Open market plans renew on their own date.
Is Justworks a PEO?
Yes. Justworks sells a payroll-only service and two PEO plans, and health insurance sits with the PEO. Its pricing page lists Justworks Payroll at $8 a month per employee plus a $50 base fee, PEO Basic at $79 a month per employee, and PEO Plus at $124. Its FAQ there says PEO Plus adds access to medical, dental, and vision coverage “through large group or small group plans.” To join the PEO, a company needs at least two W-2 employees.
By our math, the step from Basic to Plus is $45 a month per employee, or $540 a year. That’s Justworks’ fee for the service, and the insurance premiums come on top of it. Payroll customers can add health insurance for $8 a month per benefits-eligible employee. Any plan can also offer health insurance reimbursements instead, through a CHOICE arrangement (formerly called an ICHRA) run with a partner, Thatch, for $25 a month per enrolled employee.
In the registration statement Justworks filed with the SEC in June 2022 for a planned stock offering, it said the IRS certified it as a professional employer organization in 2017. A certified PEO is generally solely liable for the federal employment taxes on the wages it pays. Our post on what a PEO is covers co-employment in more detail.
Master policy or open market: what’s the difference?
A master policy plan puts your employees on a large group plan that Justworks sponsors for many businesses under one policy. An open market plan is a small group plan your company holds itself, with Justworks helping set it up. Justworks’ help article on large group vs small group health insurance lays out how the two differ:
| Master policy (large group) | Open market (small group) | |
|---|---|---|
| Who holds the policy | Justworks, covering many companies | Your company |
| Carriers named | Aetna, Kaiser, and UnitedHealthcare, depending on where your company is based | Blue Cross Blue Shield plans, UnitedHealthcare, and Kaiser, varying by state |
| How the price is set | Underwriting on your team’s demographics and past health insurance use | The carrier’s rates for your area, by age or as one blended rate per coverage tier |
| Who approves mid-year changes, like a new baby | Justworks | Your company, as plan administrator |
| How premiums are paid | Through Justworks | Straight to the carrier by automatic bank payment |
| When it renews | Justworks’ plan year, November 1 to October 31 | A year after your coverage started |
Sources: Justworks help center articles on large group vs small group plans, open market pricing, and 2026-2027 renewals, checked November 12, 2026.
Justworks says it decides which kind to quote based on your company’s size and needs, and looks at it again every year at renewal. Its list of open market carriers covers all 50 states. In 16 of them, including California, New York, Texas, and Illinois, a Blue Cross Blue Shield plan or Kaiser is on the list. In the other 34, the only carrier is UnitedHealthcare or its Oxford plans. In Florida, for example, the open market carrier is UnitedHealthcare, whose three Florida companies are raising small business rates 16.7% to 17.4% for 2027.
Large group plans also come with Justworks’ supplemental benefits (accident, critical illness, and hospital coverage that pays cash), which aren’t offered with open market plans yet.
How Justworks sets your health insurance price
On a master policy, your price starts with your own group. Justworks requires information about your team’s demographics and past health insurance when you join, so carriers can set a starting rate. Each year after that, its article on large group renewal rates says the carriers adjust it based on what your group’s claims show, the plans you offer, who’s enrolled, and how they expect your team to use care. Broad costs count too: the industry’s results, how plans perform in your region, new required benefits, drug prices, and inflation.
That’s experience rating, where your own claims move your price. Justworks says ongoing costs, like a long-term need for brand-name drugs, tend to affect a renewal more than a one-time expense like a birth. It also says it can’t break down any one customer’s renewal rate, because the carriers price these factors in their own ways. Our post on how claims affect a renewal explains the idea.
Open market plans are priced like any small business plan under the ACA. The carrier sets rates at a broad level with the state, either by each person’s age (age-banded) or as one blended rate per coverage tier (composite). Justworks says carriers refresh these rates every quarter, and your group’s rate is locked for a year until its renewal.
As of its 2022 filing, Justworks didn’t carry the claims risk on its medical plans. It said all of its medical insurance was on policies where the carriers set the premiums and Justworks wasn’t responsible for any deductible. It carried some claims risk on dental, vision, and short-term disability plans starting November 1, 2021. The four public PEOs in our PEO guide all carry part of their health plans’ claims. We didn’t find a newer public statement from Justworks on this.
What changes at a Justworks renewal?
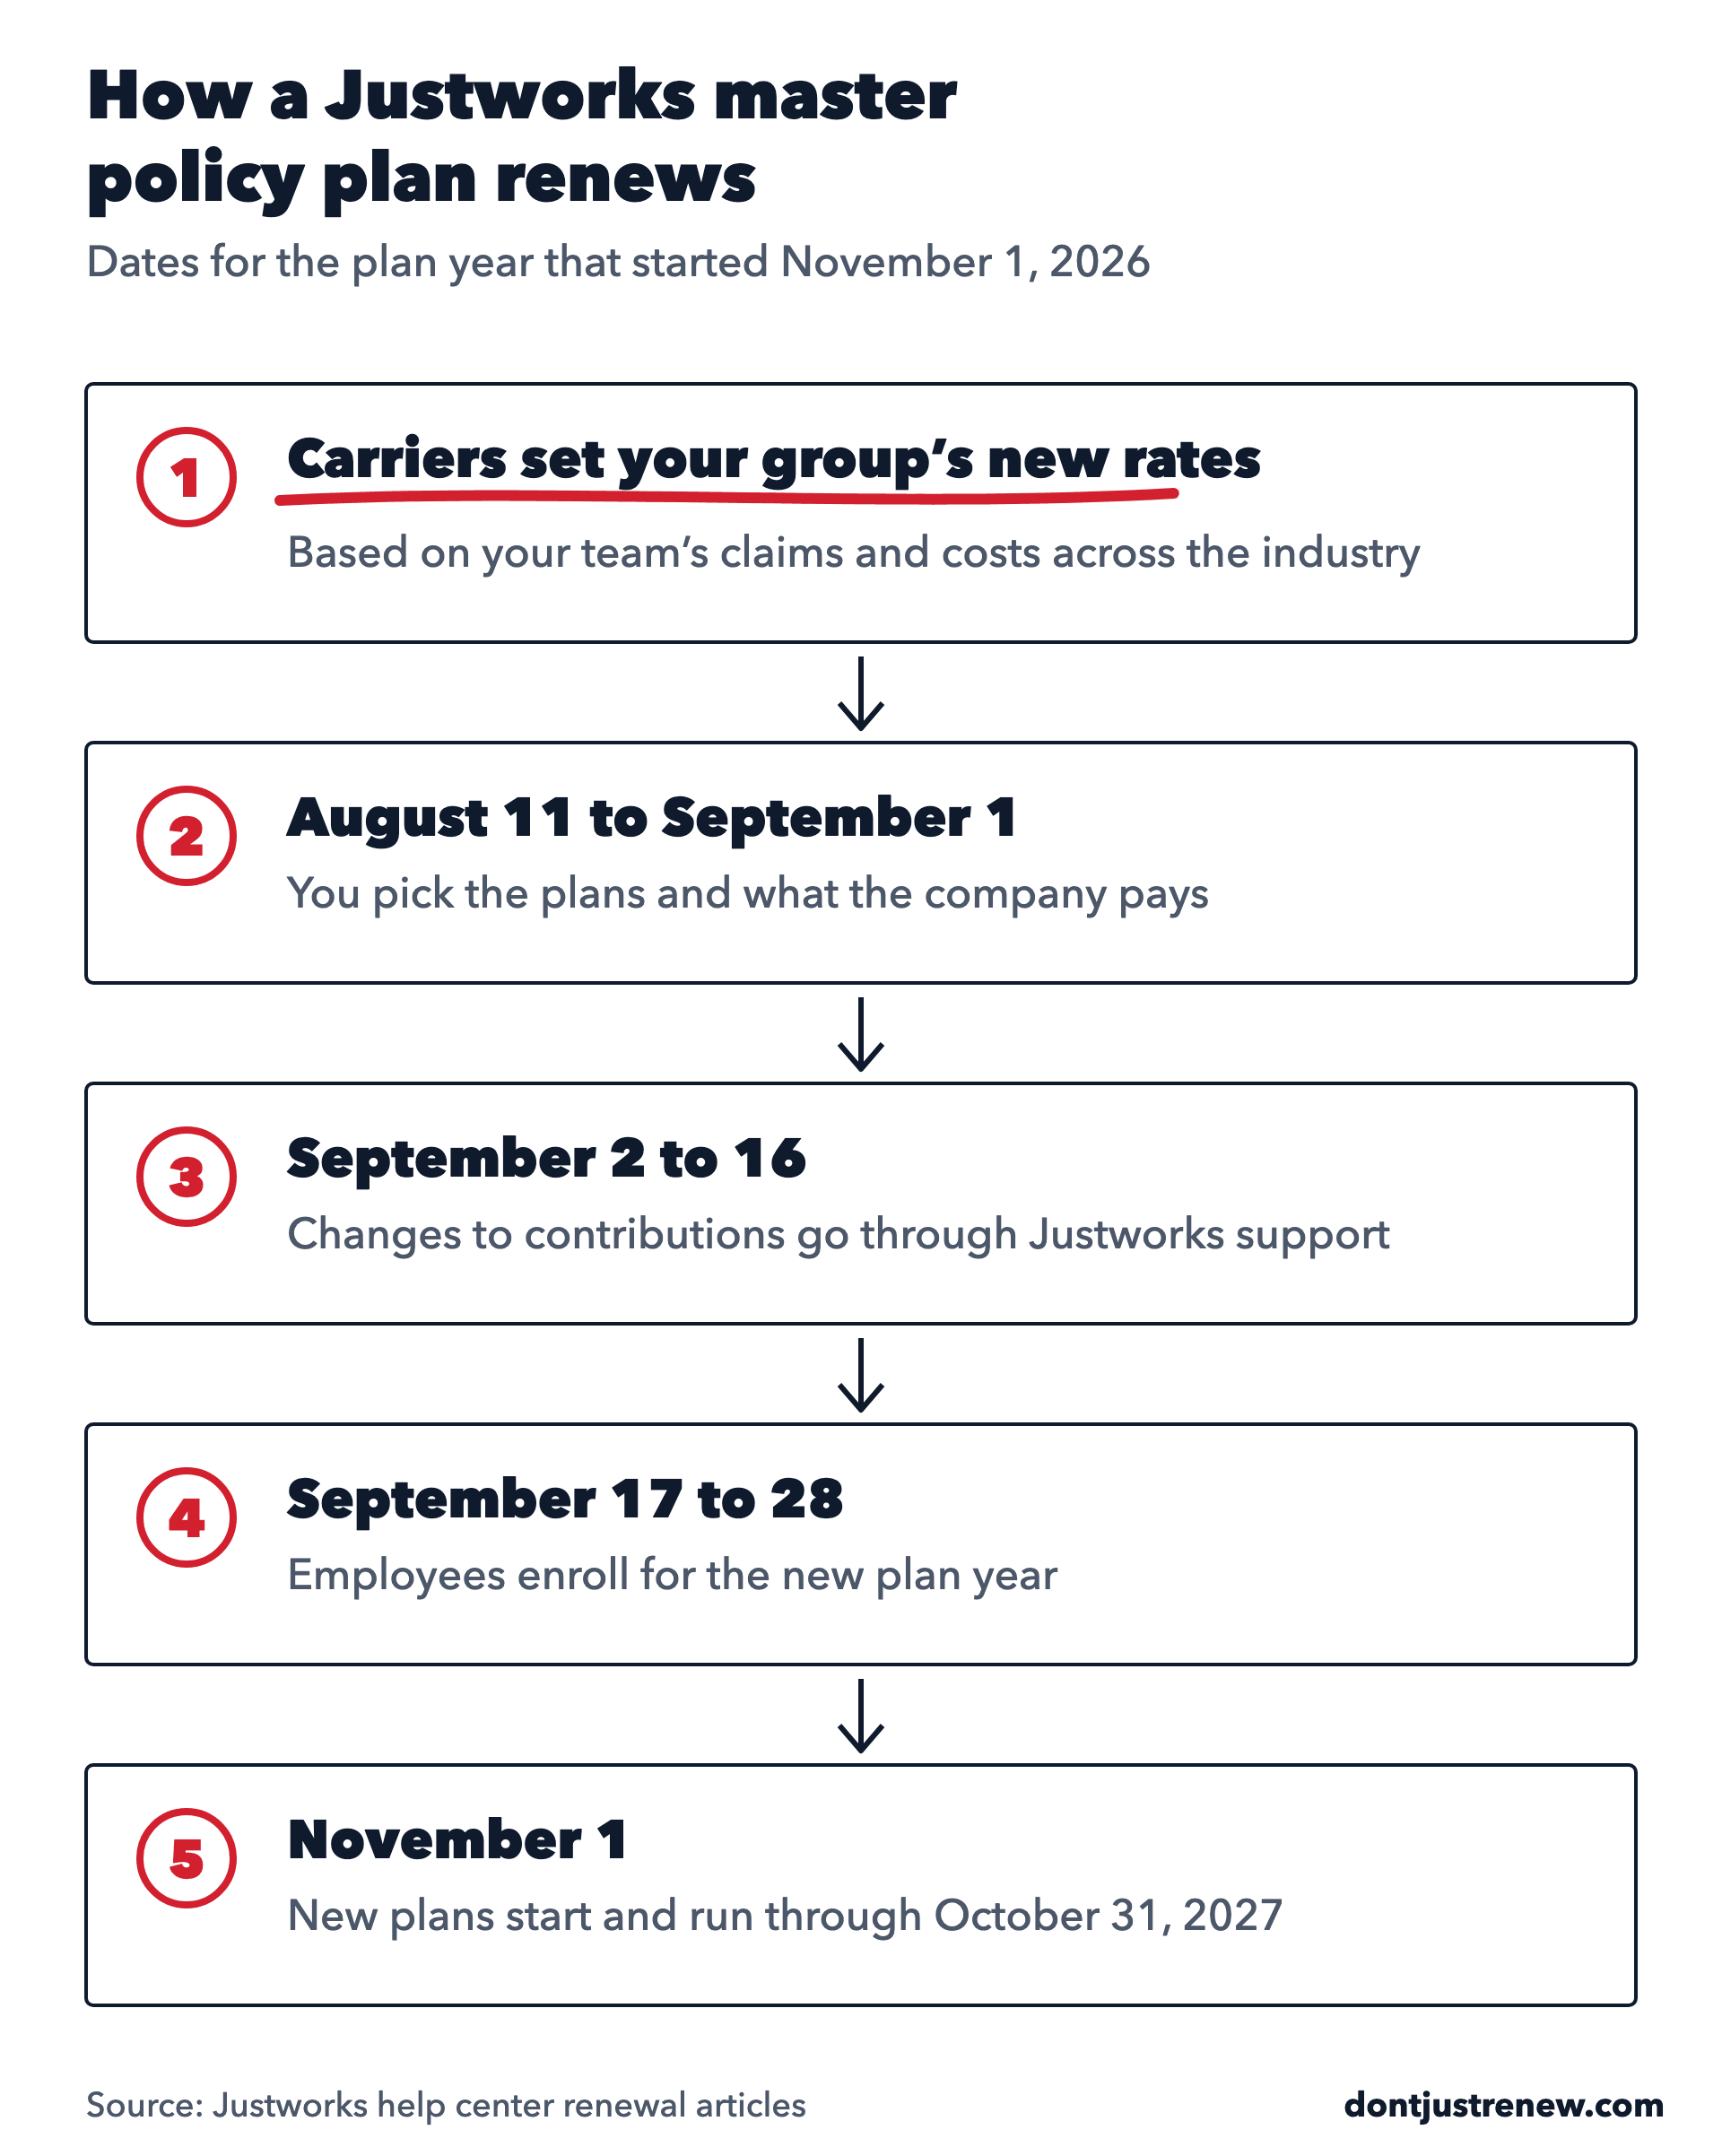
For master policy plans, everyone renews at once. For the plan year that started November 1, 2026, employers picked plans and contributions from August 11 to September 1, could ask support to change contributions until September 16, and employees enrolled from September 17 to 28. An employee who did nothing kept the same plan if the company still offered it. If it didn’t, Justworks moved them to the lowest-cost plan offered.
Some companies get moved between the two kinds at renewal. When a company switches from a master policy plan to an open market plan, its employees have to enroll during open enrollment or they lose medical coverage, according to Justworks’ renewal FAQ. Open market plans don’t follow the November calendar. Their renewal depends on when the coverage started.
Renewal is also when companies tend to leave. Justworks’ 2022 filing said more customers leave during health insurance renewal periods and the turn of the calendar year, which can pull its retention numbers down in those quarters.
Who tends to use Justworks
Small companies, judging by its last public numbers. In its 2022 filing, Justworks said it passed 7,800 customers and 118,000 worksite employees (people working at its client companies) in 2021. By our math, that’s about 15 employees per customer. The same filing named Aetna, Kaiser Permanente, MetLife, and UnitedHealthcare among the carriers it works with.
For a company that size, the master policy is a way into large group plans, which carriers usually reserve for employers with at least 51 or 101 benefits-eligible employees, depending on the state. A small group plan through the open market follows the usual small business rating rules instead, where your own claims can’t change your rate.
What to check on a Justworks health plan
- Which kind you’re on, master policy or open market. It decides how your rate is set and when you renew.
- On a master policy, what changed in your enrollment and plan mix since last year, since Justworks says those feed your renewal rate.
- On an open market plan, your renewal date and whether your rates are age-banded or composite.
- The carrier’s minimum participation rules, which Justworks says are checked when you enroll and again at each renewal.
Don’t Just Renew is not associated with, endorsed by, or sponsored by Justworks. Its name is a trademark of its owner, and we use it only to describe public information. This article is general information, not insurance, tax, or legal advice. Figures are current as of November 12, 2026.