 Don’t just renew
Sharp Health Plan small business plans in California: 12.3% for 2027, its biggest increase in at least two years
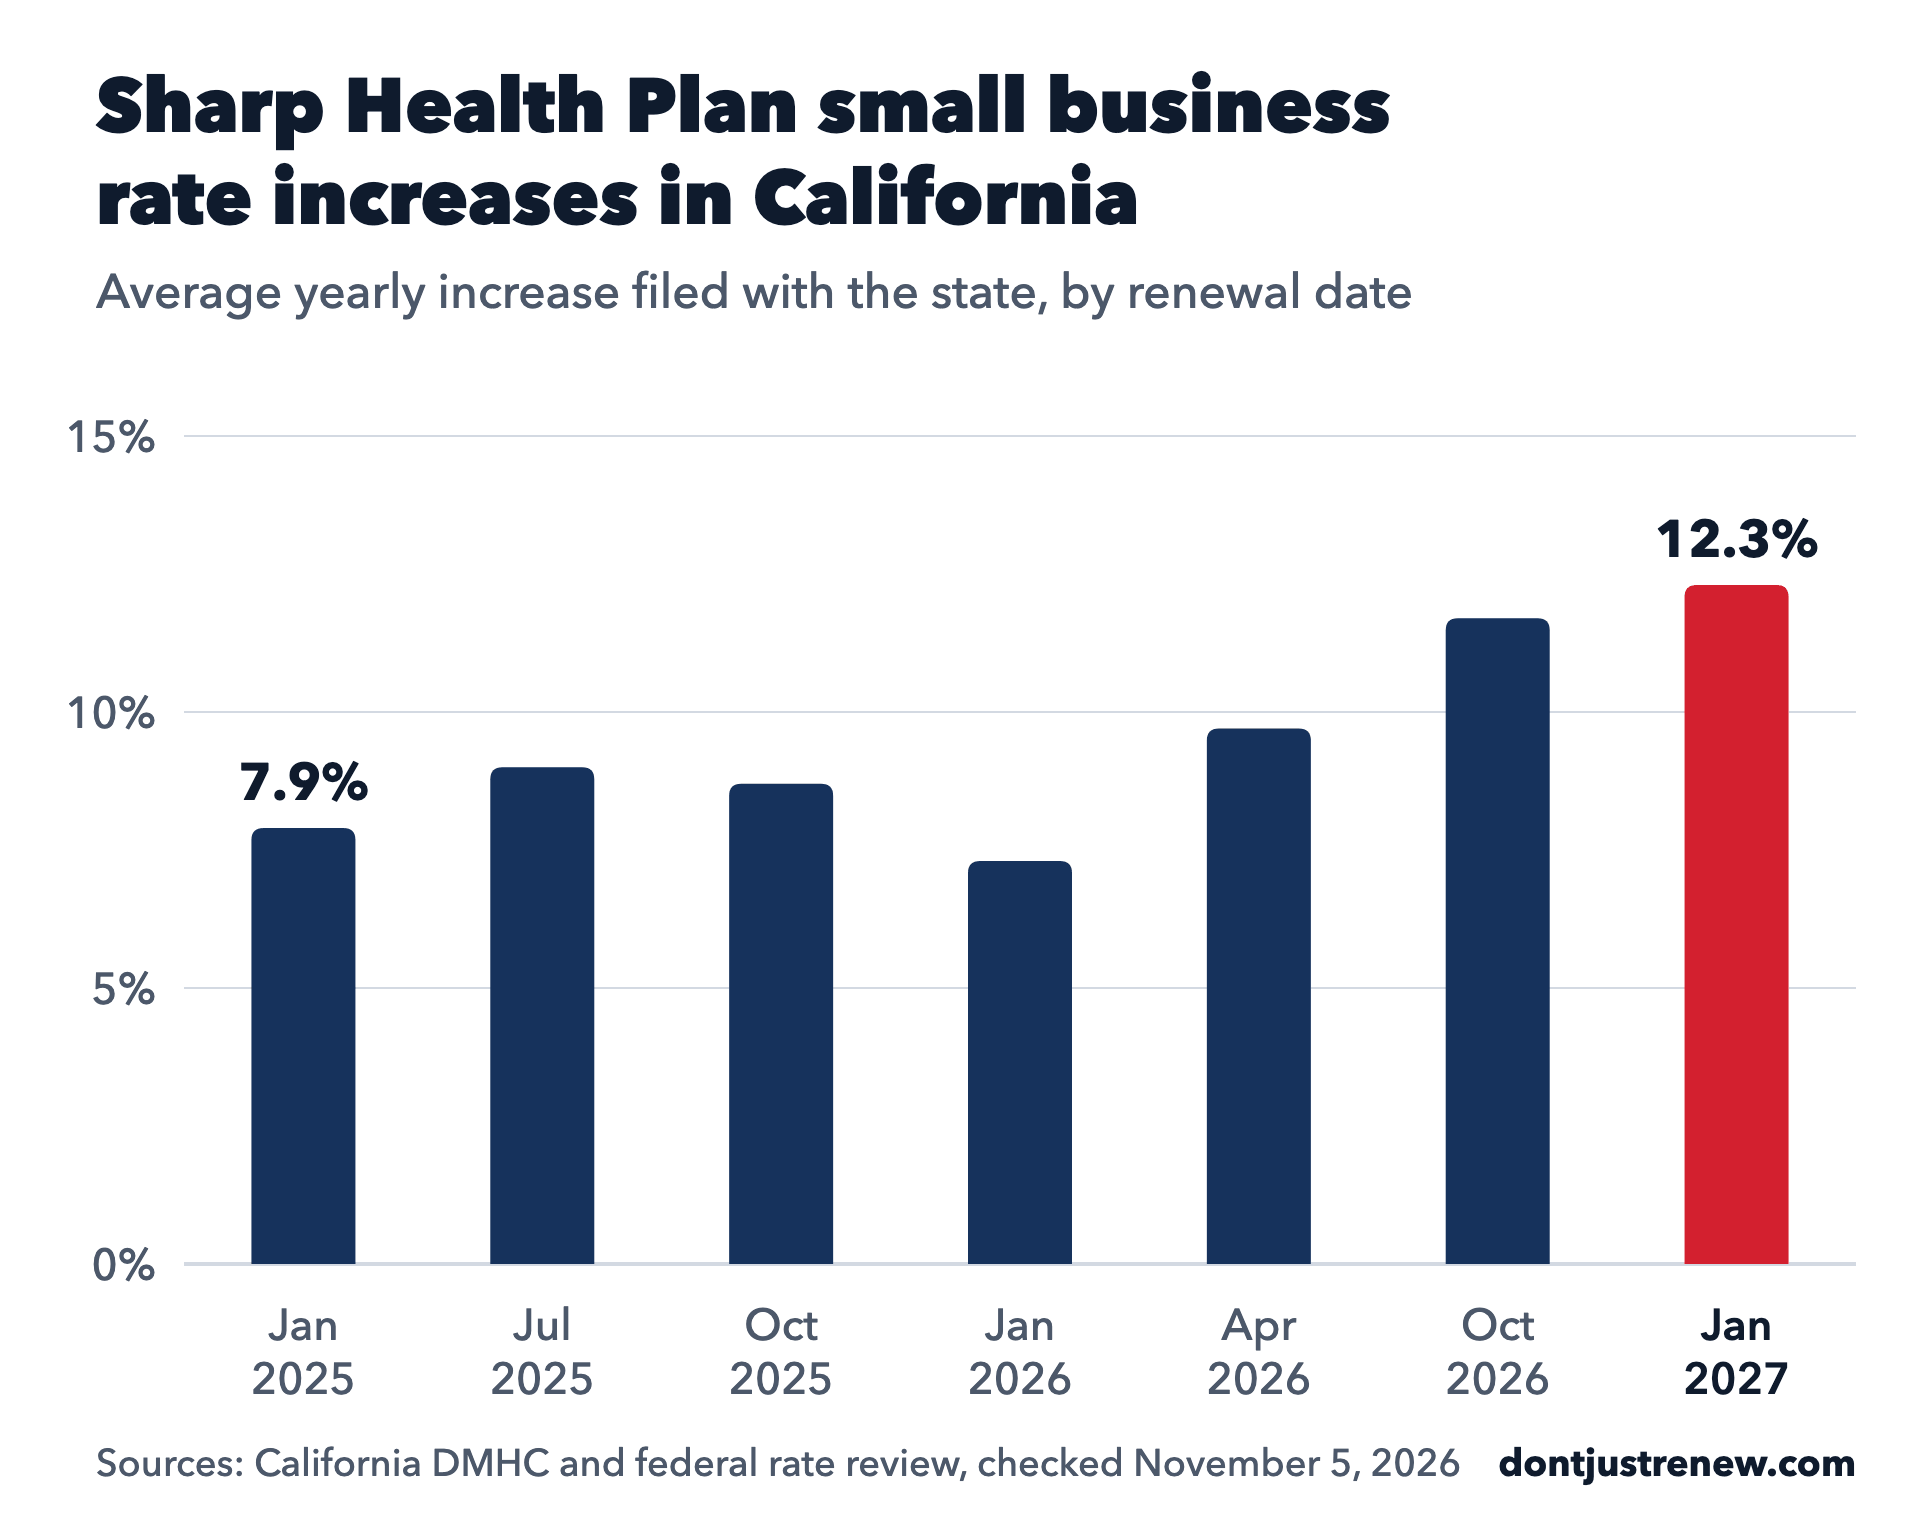
Sharp Health Plan has the lowest average premium of any California small business plan we’ve covered, about $626 a month per person after renewal. It’s also rising faster than it was. Sharp’s January 2027 increase is 12.3%, up from 7.3% a year earlier, and each of its last three filings has been its highest in two years.
In brief
- Sharp’s small business plans are going up 12.3% on average for January 2027 renewals. Individual plans range from 7.9% to 15.9%.
- That’s about $69 more a month per person on average, by our estimate.
- Sharp’s HMO average of $628 per person is the lowest HMO average among the eight California plans we’ve covered.
- Sharp expects to pay about $86 per member each month into the federal risk adjustment program, roughly 14% of its average premium.
A San Diego plan, mostly HMOs
Sharp Health Plan sells mostly HMOs in San Diego County and southern Riverside County, and most of its small business members are in San Diego, according to its actuarial memo. Its January 2027 filing covers 21,523 people at companies with 1 to 100 employees.
Sharp files with the Department of Managed Health Care (DMHC), the state agency that oversees health plans, most quarters. DMHC lists the January increase as 12.3% as filed. The federal rate review site lists 12.28% as final, with the review finding it “not unreasonable.”
Each of the last three filings set a new high
Through early 2026, Sharp’s increases sat between about 7% and 9%. Then came 9.7% for April 2026, 11.7% for October, and 12.3% for January 2027. Two January renewals in a row at the average rate, 7.3% and then 12.3%, add up to about 20.5%, by our math.
| Renewal date | Sharp Health Plan |
|---|---|
| January 2025 | 7.9% |
| April 2025 | No filing |
| July 2025 | 9.0% |
| October 2025 | 8.7% |
| January 2026 | 7.3% |
| April 2026 | 9.7% |
| July 2026 | No filing |
| October 2026 | 11.7% |
| January 2027 | 12.3% |
Sources: DMHC rate filings for Sharp’s non-grandfathered small business plans, checked November 5, 2026, and the federal rate review site, which lists the same quarters. See the January 2027 DMHC filing and Sharp’s filing summary.
Sharp also has 565 people on older plans from before 2014, called grandfathered plans. Those went up 14.7% in October 2026.
How Sharp’s prices compare
Even after this increase, Sharp’s HMOs carry the lowest average premium of the California HMOs we’ve looked at.
| Plan | Average HMO premium |
|---|---|
| Sharp Health Plan | $628 |
| Aetna Health of California | $664 |
| Kaiser Permanente | $709 |
| UHC of California | $709 |
| Anthem Blue Cross | $737 |
| Blue Shield of California | $780 |
| Western Health Advantage | $803 |
| Sutter Health Plan | $817 |
Sources: the rate filing workbook attached to each plan’s 2027 small business filing with DMHC, checked November 2 to 7, 2026. Most figures are for January to March 2027 renewals. Kaiser’s is for all of 2027, and Sutter’s covers every month in its filing and all its plans, which are all HMOs.
Treat this as a rough guide, not a quote. Each average reflects that plan’s own members: their ages, where they live, and whether they’re on bronze or platinum plans. Sharp’s members are concentrated in San Diego, while Kaiser, Anthem, and Blue Shield average across the state. What the table does show is that Sharp’s 12.3% is coming off a lower base, so it adds fewer dollars than the same percentage would at most other plans.
Where the 12.3% comes from
Mostly the cost of care. Sharp’s filing splits the increase into parts. Higher prices and more use of care add about 10.6 points. Risk adjustment adds 2.1 points, and a higher profit margin adds 1.3. Plan design changes take 1.7 points off. Taxes, fees, and administrative costs barely move the total.
The filing expects costs to rise 9.2% a year, with medical care at 8.8% and prescription drugs at 12%. Sharp’s filing summary points to higher prices from doctors, hospitals, and drug companies, more people using care, more expensive treatments, and new state laws that raise drug costs.
Risk adjustment is the piece that stands out. It’s a federal program that moves money between insurers based on how healthy their members are, and plans with healthier-than-average members pay in. Sharp paid about $70 per member each month for 2025 and expects to pay about $86 in 2027. Against a $626 average premium, that’s roughly $1 of every $7.
Sharp pays most of its doctors and hospitals a set amount per member each month instead of a fee for each visit. Those payments made up about 82% of its small business medical and drug costs in 2025. That year it spent 82.9% of its revenue from these plans on claims, above the 80% federal minimum. Its margin for profit and risk goes up to 2.0% of premium for 2027.
Your plan may cover a bit less in 2027
The 1.7 points that plan design changes take off the increase come from higher copays and deductibles. Covered California changed its standard small business plan designs for 2027, and Sharp adjusted its other plans to meet federal rules on how much of the cost a plan has to cover. In most cases, employees will pay a little more when they get care, which is part of why the premium increase isn’t higher.
| Plan type | People covered | Average increase | Average monthly premium per person |
|---|---|---|---|
| HMO | 20,681 | 12.3% | $628 |
| High-deductible plan | 744 | 13.3% | $519 |
| Point-of-service (POS) | 98 | 12.4% | $1,042 |
| All plans | 21,523 | 12.3% | $626 |
Source: the rate filing workbook attached to Sharp Health Plan’s January 2027 DMHC filing, checked November 5, 2026. Premiums are averages across ages and plans.
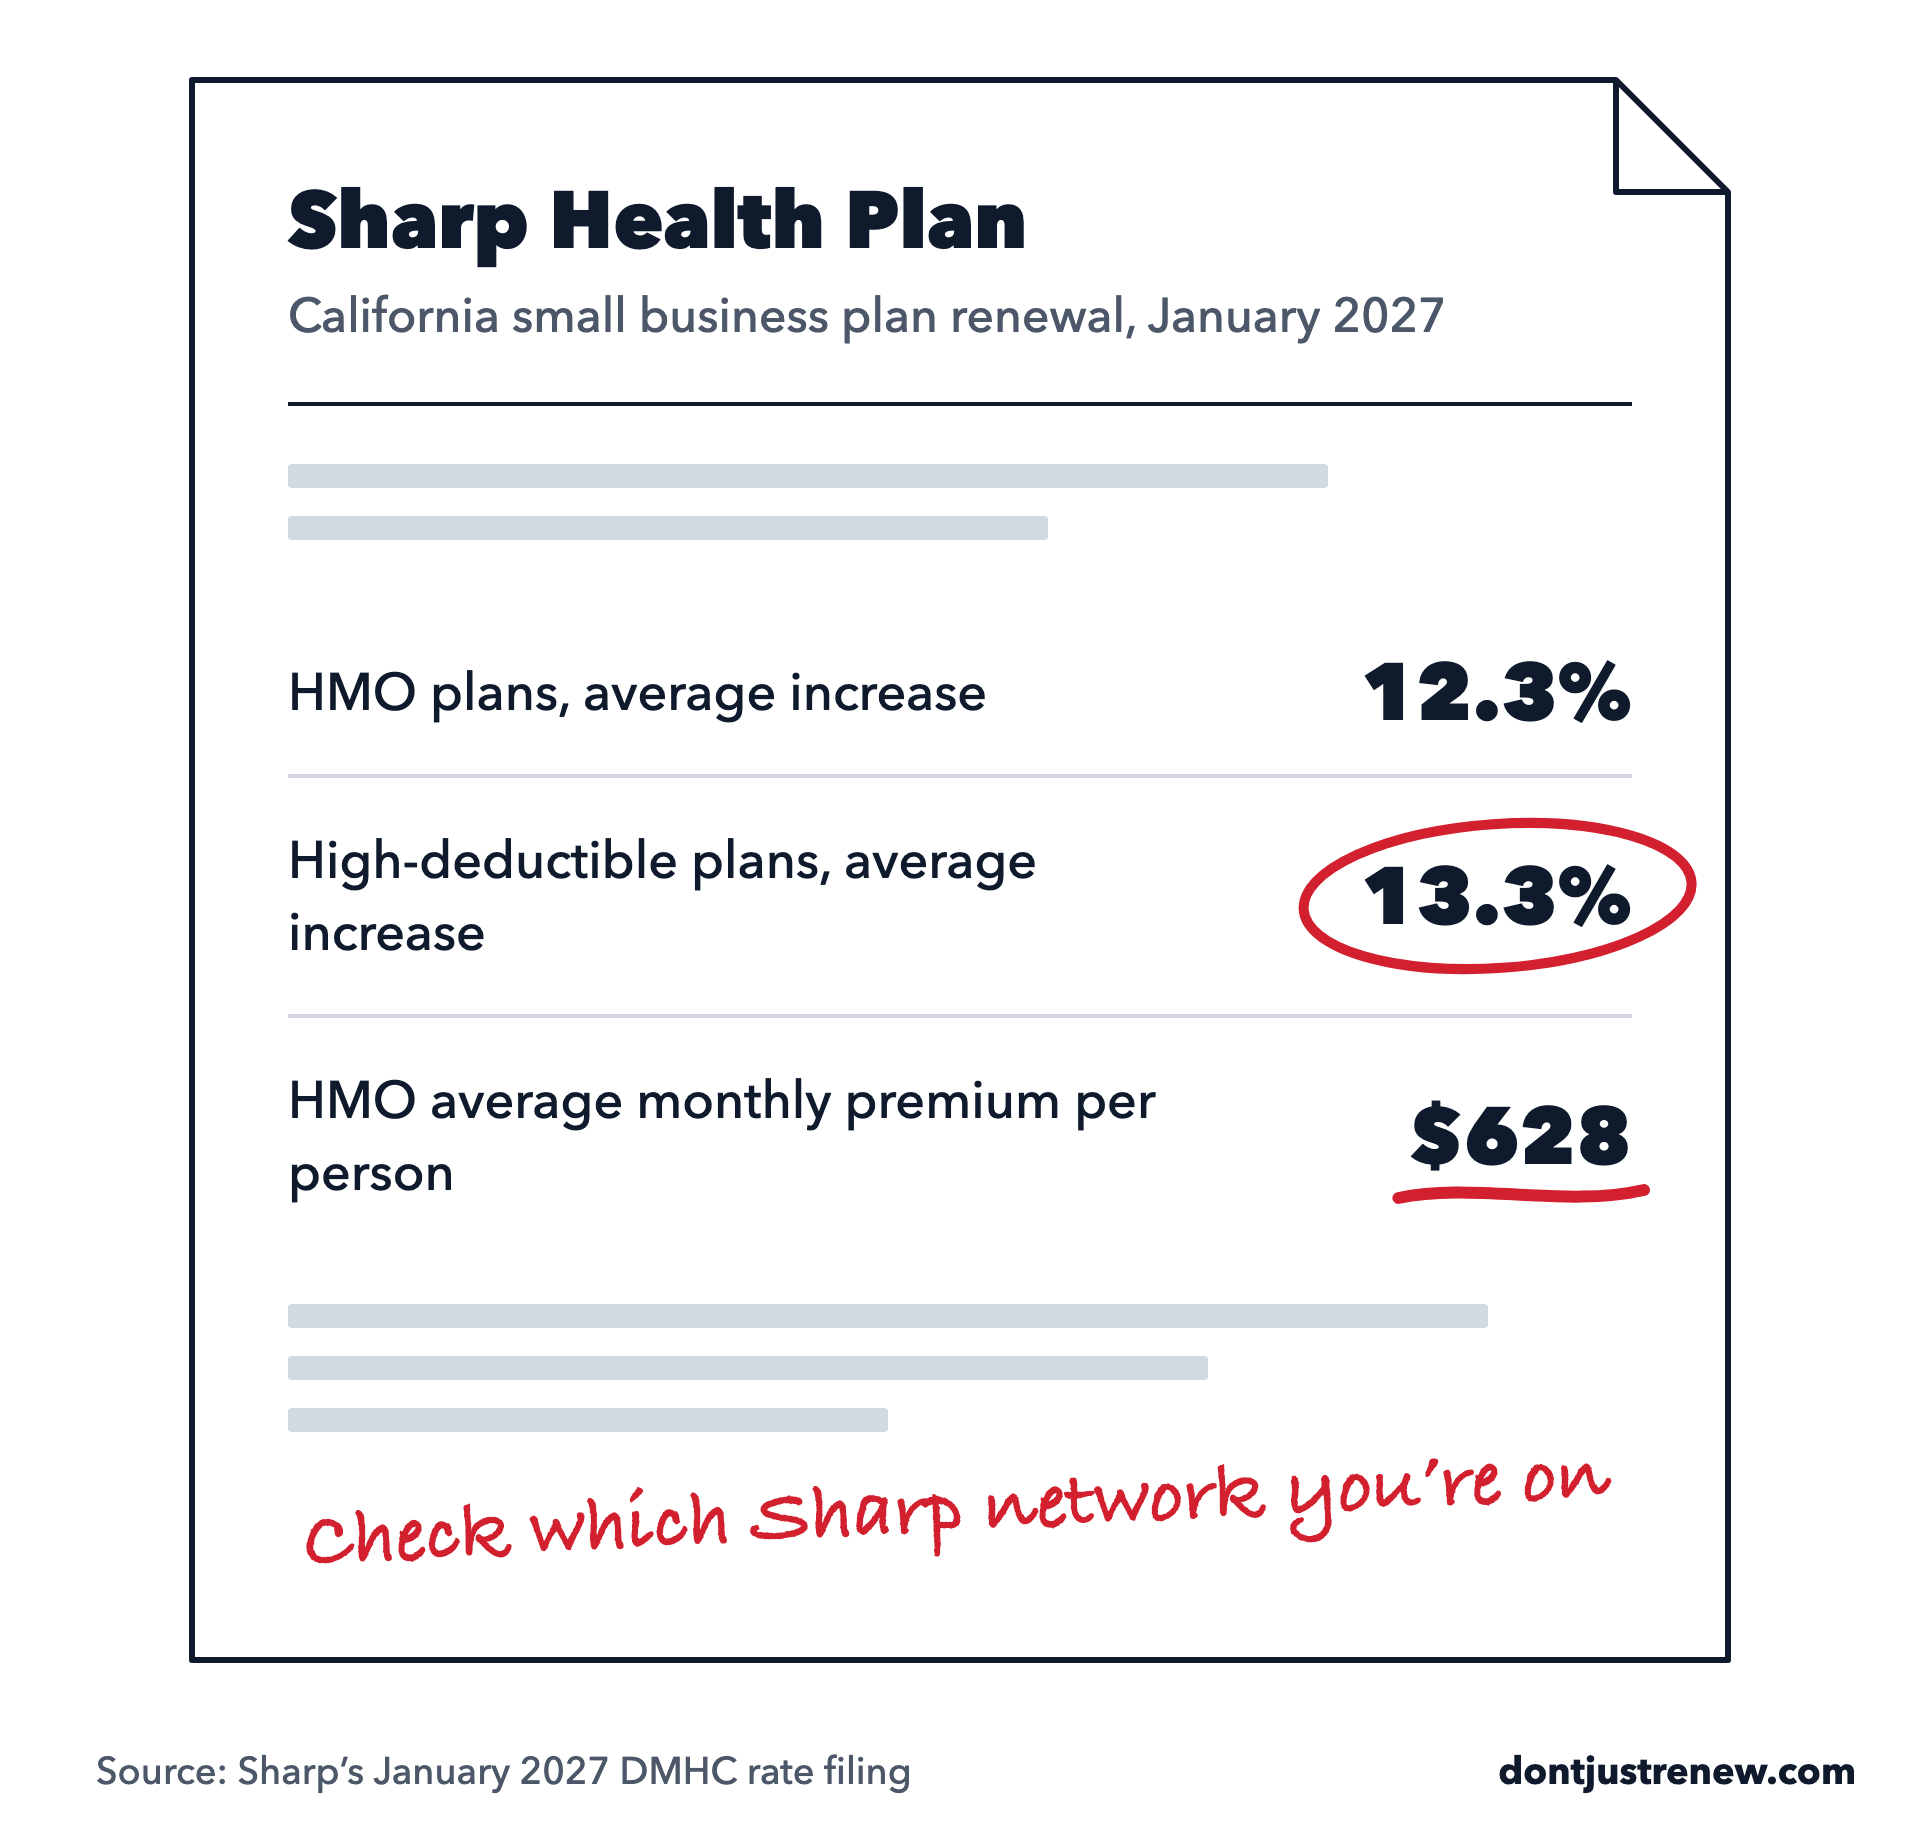
Nearly everyone is on an HMO, which keeps people in a set network of doctors and hospitals. The high-deductible plans are rising fastest, at 13.3%, though they’re still the cheapest. The few point-of-service plans add some coverage outside the network and cost about $400 more per person than the HMOs.
Statewide, Sharp’s 12.3% lands near the middle of January’s filings, below Blue Shield’s 13.9% and above Anthem’s 10.9%, according to DMHC.
A checklist for Sharp groups
- Find your plan’s own rate on the notice. With a range of 7.9% to 15.9%, the average may be far from yours.
- Check which Sharp network your plan uses. In southern Riverside County, employers can buy only the off-exchange plans on its Value and Choice networks.
- Compare this year’s copays and deductibles with next year’s. Most Sharp plans changed them.
- If you offer the high-deductible plan, note it’s rising the most this year.
Don’t Just Renew is not associated with, endorsed by, or sponsored by Sharp Health Plan. Sharp Health Plan is a trademark of its owner, and we use the name only to report public rate data. This article is general information, not insurance advice. Figures are current as of November 5, 2026.